A new-account scam can create damage long before you see the first bill. That is why understanding credit freeze versus fraud alert matters when you are protecting a score you have worked hard to rebuild. Both tools are free, federally protected options that can reduce identity-theft risk. But they do not work the same way, and choosing the wrong one can leave gaps at the worst possible time.
If you are preparing for a mortgage, auto loan, rental application, or credit repair process, the goal is simple: protect your file without creating unnecessary delays when a legitimate lender needs to review it.
Credit Freeze Versus Fraud Alert: The Core Difference
A credit freeze, also called a security freeze, restricts access to your credit report. In most cases, a lender cannot pull your report to open a new account unless you lift the freeze first. Because most new creditors rely on a credit report before approving an application, a freeze is generally the stronger barrier against someone opening credit in your name.
A fraud alert does not block access to your report. Instead, it tells potential creditors that they should take extra steps to verify your identity before granting new credit. For example, a lender may call the phone number listed on your alert before approving an application. The report can still be accessed, and the final verification process depends on the creditor.
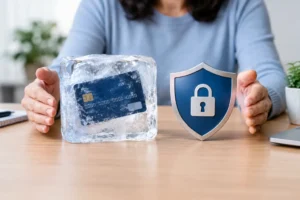
Think of a freeze as a locked door. A fraud alert is a warning sign asking visitors to confirm who they are before they enter. Both can help, but a locked door provides more control.
What a Credit Freeze Does and Does Not Do
A security freeze can be placed with each of the three nationwide credit bureaus: Equifax, Experian, and TransUnion. You need to freeze all three reports for the strongest protection because a lender may use any one of them when reviewing an application.
Once a freeze is in place, you can still review your own credit, dispute inaccurate information, and maintain your existing credit cards and loans. Your current creditors can generally continue accessing your report for account management, collections activity, or credit-limit reviews. A freeze does not shut down your accounts or change the information already appearing on your reports.
It also does not stop every kind of fraud. If someone already has access to an existing credit card number, bank account, or online login, they may still attempt unauthorized transactions. You should continue checking account activity, using strong passwords, and responding quickly to suspicious notices.
The trade-off is convenience. Before applying for a new credit card, apartment, auto loan, mortgage, personal loan, or some utility services, you may need to temporarily lift the freeze. You can usually schedule a lift for a specific period or provide access to a specific creditor. Plan ahead so a lender does not pull your report while it is still frozen and delay your approval.
What a Fraud Alert Does and Does Not Do
A standard initial fraud alert usually lasts one year. You can place it with one credit bureau, which is then responsible for notifying the other two. That makes it a practical choice if you have reason to be cautious but still expect to apply for credit soon.
A fraud alert can be useful after a lost wallet, a phishing attempt, suspicious mail, or signs that your personal information may have been exposed. It may also make sense when you want lenders to take an extra look without needing to manage a freeze lift for every upcoming application.
However, a fraud alert is not a guarantee that fraudulent accounts will be stopped. It relies on creditors following verification procedures, and those procedures can vary. If you know your Social Security number or other sensitive information was compromised, a freeze is usually the more protective response.
Consumers who submit an identity theft report may qualify for an extended fraud alert that lasts seven years. An active-duty alert is also available for eligible military service members. These options offer longer protection, but they still do not restrict report access as firmly as a security freeze.
When a Freeze Is Usually the Better Choice
A credit freeze is often the right move when you are not planning to seek new credit in the near future and want the strongest practical protection against new-account fraud. It is especially worth considering after confirmed identity theft, a major data breach involving your personal information, or an unexplained hard inquiry that you did not authorize.
It can also help people who are focused on repairing damaged credit. When you are disputing inaccurate collections, late payments, charge-offs, or unauthorized inquiries, the last thing you need is a fraudster adding new accounts to the problem. A freeze will not remove negative items, but it can help prevent fresh credit damage while you work to correct your reports.
Freezes are free to place and lift under federal law. The process is manageable, but you need to stay organized. Keep confirmation details securely stored, know which bureaus are frozen, and give yourself time before a major loan application.
When a Fraud Alert May Be the Better Fit
A fraud alert may be the more convenient option when you expect lenders or landlords to review your credit in the coming weeks. If you are shopping for a car, comparing mortgage offers, applying for rentals, or opening a needed account, an alert avoids the extra step of unfreezing your reports.
It may also be appropriate when your concern is real but limited. Maybe you received a suspicious email, lost a document, or learned that a company you used had a breach. A fraud alert adds a layer of caution while keeping your credit available for normal applications.
Still, convenience should not outweigh risk. If you have evidence that someone has already used your information, do not rely on an alert alone. Consider a freeze, review all three credit reports closely, contact affected creditors, and document every step you take.
Protecting Your Credit While Applying for a Loan
The timing of a freeze matters. If you are preparing for a mortgage or auto loan, ask the lender which credit bureau it expects to use and when it plans to pull your report. Then lift your freeze before the pull is scheduled. Some lenders may need access more than once during underwriting, so ask whether a short temporary lift is enough.
Avoid repeatedly applying for new credit while you are trying to qualify for a major loan. Multiple hard inquiries can create confusion, and new balances or accounts can affect your score and debt-to-income picture. A fraud alert or freeze protects against unauthorized applications, but neither replaces smart application timing.
This is also the right time to review your reports for incorrect negative information. Look for accounts that do not belong to you, inaccurate late payments, duplicate collections, wrong balances, or hard inquiries you never approved. Identity theft and reporting errors can look similar at first, but both require prompt attention.
A Credit Freeze Will Not Repair Your Credit Report
One of the biggest misunderstandings is believing that security tools improve a credit score. A credit freeze and a fraud alert do not raise your score, remove collections, erase late payments, or delete legitimate charge-offs. They are preventive tools, not credit repair solutions.
If your report contains inaccurate or unverifiable negative items, you may need a separate dispute strategy. That can involve reviewing documentation, challenging errors with the credit bureaus, and following up when information is not properly corrected. The process can feel overwhelming when you are also trying to secure financing or recover from identity theft.
Express Credit Boost helps consumers address negative credit-report items with a personalized approach focused on real progress. Whether you are dealing with questionable inquiries, late payments, collections, or charge-offs, knowing what is hurting your profile is the first step toward a stronger application.
The Practical Choice for Your Situation
Choose a credit freeze when protection is your priority and you do not need regular access to new credit. Choose a fraud alert when you want creditors to verify your identity but expect to apply for credit soon. In some situations, people start with a fraud alert and move to a freeze once they have confirmed a greater risk.
Do not wait for a denial, collection notice, or unfamiliar account to start paying attention. Review your reports, protect your personal information, and take action when something does not look right. A few focused steps now can help preserve the credit opportunities you are working to earn.